US nonprofit reporting preparation requires more than a year-end financial export. The organisation needs to know which return or notice applies, which reporting year is involved and what non-financial information supports the submission. ERP can organise records and reconciliations, but a chart of accounts alone cannot answer every filing question.
Start with the organisation's status and reporting obligations, then map the relevant information to its source and reviewer. Keep federal filing preparation distinct from state, donor and other requirements. They may use overlapping records without having identical scope or definitions.
Which filing applies to this US entity?
The Internal Revenue Service's Form 990 instructions explain filing requirements, exceptions and the relationship to other returns or notices. Not every nonprofit files the same form. The organisation's status and circumstances need to be assessed before choosing a reporting template.
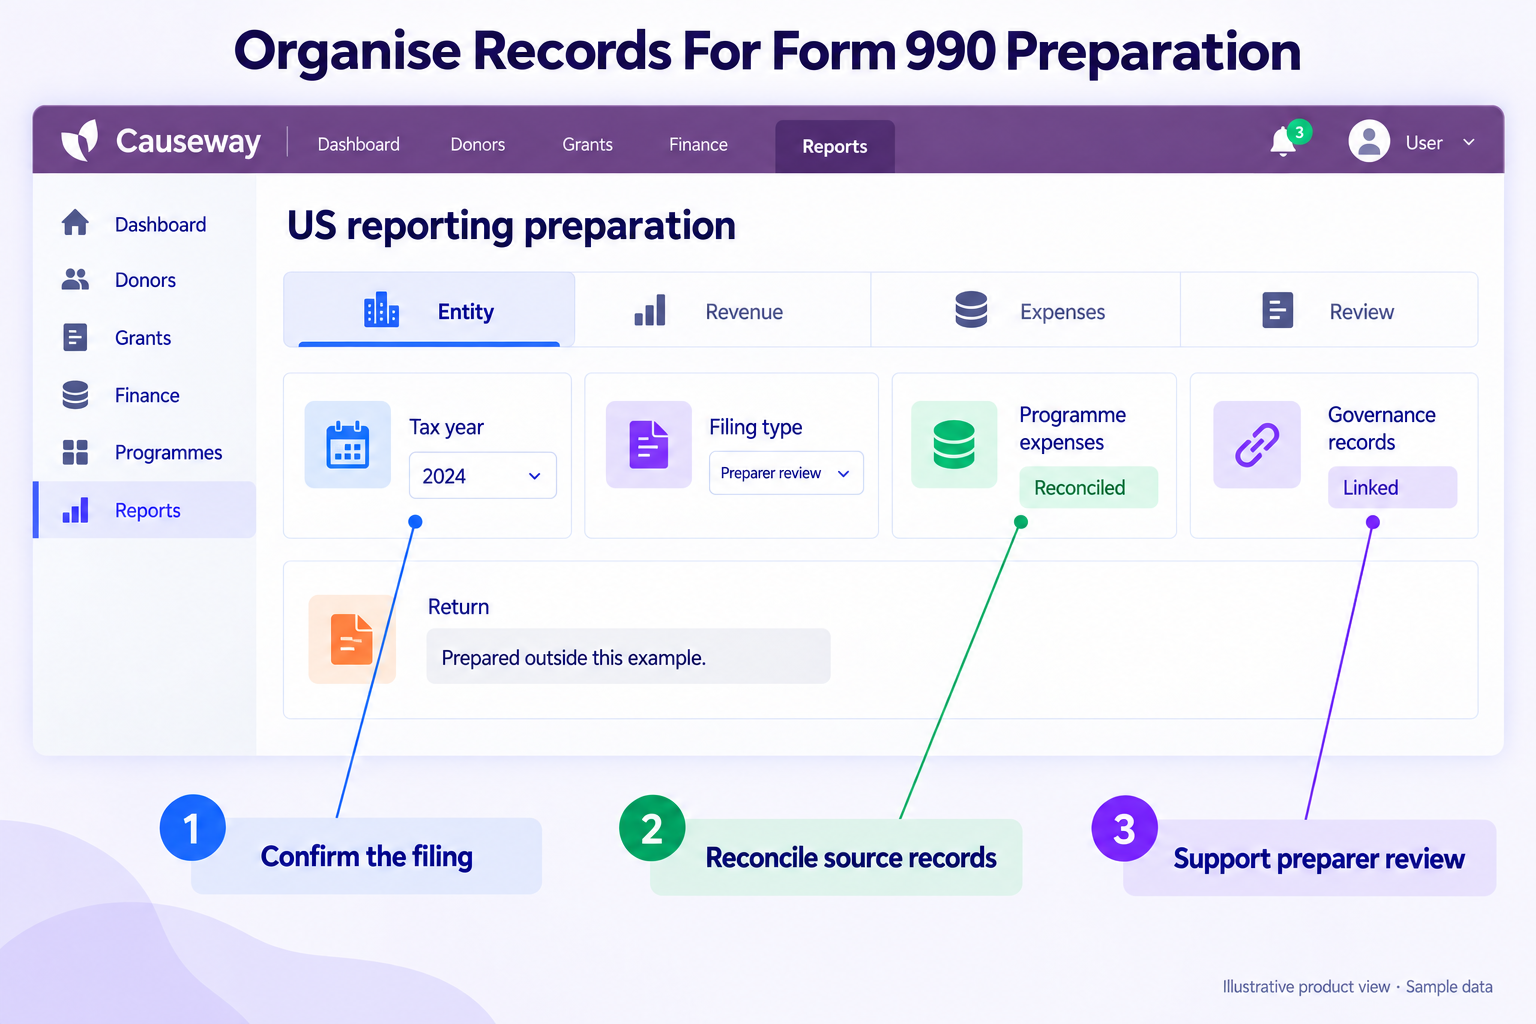
Record the entity, tax year, applicable filing and basis for the determination. Assign responsibility for reviewing exceptions and related obligations. The compliance register helps keep this decision separate from the software configuration that supports it.
Do not infer federal tax-exempt status from an organisation's nonprofit incorporation alone. Obtain the relevant records and qualified tax review. If several entities are involved, specify which records and activities belong to the filing organisation rather than assuming a group dashboard is the filing population.
Financial and programme records feed different return fields
Build a field-to-source worksheet for the applicable return and schedules. Identify which items come from reviewed financial records, programme activity, governance information or other sources. Give each field an owner and evidence reference.
| Information Area | Preparation Question |
|---|---|
| Revenue and expenses | Which reviewed accounts and mappings support the amount? |
| Programme activities | Who validates the description and activity evidence? |
| Governance information | Which responsible person confirms the answer? |
| Related records | Are entity and period boundaries consistent? |
| Attachments or schedules | What triggers the requirement and who reviews it? |
The mapping should follow the current instructions and the organisation's circumstances. Do not assume that an ERP report named “Form 990” includes every required statement, schedule or review for your filing.
Track restricted awards and related evidence
Maintain award identifiers, agreements, approved budgets and allocation records. Distinguish donor conditions from internal designations in the fund accounting records. Accounting treatment and return presentation require the appropriate finance or tax decisions rather than automatic inference from a grant label.
As a preparation exercise, select one award supporting two programmes. Trace its receipts, expenditure and allocation evidence, then identify how the relevant amounts enter the reporting workpapers. Check that the same cost is not counted in both programmes simply because the award is linked to both.
Retain supporting programme descriptions and the review of material statements. A financial total cannot independently validate a claim about results or the population served. Keep narrative evidence and financial reconciliation connected but separate.
The workpaper must explain every adjustment
Reconcile the reporting workpapers to the reviewed financial records using the applicable definitions. Explain differences in classification, period or reporting treatment. A spreadsheet adjustment should have a reason and reviewer rather than being an unexplained amount inserted to make totals agree.
The local reporting configuration should preserve mapping versions and historical outputs. If a prior-year correction is identified, assess its treatment through the appropriate review process. Do not silently change a retained filed return when the current ledger is updated.
Separate preparation, review and authorisation responsibilities. Preserve the exact submitted version and confirmation. If an external preparer is involved, define how questions, revisions and final approval are communicated so the organisation retains a coherent evidence trail.
The tax year determines the instructions
Use the Form 990 instructions for the tax year being reported and check relevant updates before filing. For a 2025 return, consult the 2025 instructions; preparing it in a later calendar year does not change its reporting period.
The IRS also provides an annual returns, notices and schedules overview. Use the applicable official material with qualified review rather than relying on a vendor's static checklist for filing eligibility.
When procuring software, include the required source records, mappings and export responsibilities in the RFP. Ask suppliers to demonstrate the preparation workflow and clearly identify any external filing service or specialist work. Data preparation and electronic submission are separate capabilities.
Preserve a return preparation workpaper
For each material return line, retain the ledger source, adjustments, nonfinancial inputs and reviewer. Programme narratives, governance answers and related-party information need owners outside the posting process. Keep the final approved workpaper with the submitted version so a later ledger adjustment does not silently rewrite the explanation of an earlier filing.
Where the organisation makes covered federal sub-awards, maintain a separate partner monitoring record. That obligation should be assessed on its own terms rather than inferred from Form 990 filing status.
A return workpaper with separate owners
| Workpaper Item | Source | Preparation Result |
|---|---|---|
| Programme expense category | Reviewed ledger and allocation basis | Amount reconciles to the selected population |
| Programme description | Approved activity record | Narrative reflects the reported year |
| Governance answer | Responsible officer's confirmation | Decision and evidence retained |
| Related-party disclosure assessment | Relationship register and reviewed facts | Applicable schedule decision recorded |
For a worked $1,000 shared service allocated 60/40 to two programmes, the workpaper contains $600 and $400 with the approved basis. The combined total remains $1,000. This is an allocation example, not a prescribed Form 990 classification.
Start the year-end pack with the entity, tax year and applicable instructions. Add reconciled financial workpapers, programme and governance confirmations, and schedule assessments. Keep review issues, final approval and submission evidence with that pack. Unanswered governance questions remain open even when the ledger reconciles.
Map each obligation to its control, evidence and reviewer in the Global Compliance Controls Matrix. The return workpaper should explain how ledger, contribution, programme and governance records reach the filing.
Conclusion
The year-end workpaper should explain how ledger, contribution, programme and governance records map into the applicable return. Reconcile the totals and give every adjustment a reason and reviewer. Use the instructions for the relevant tax year, preserving the approved submission separately from later accounting changes. A completed financial export is only one input; return preparation is ready for approval when the non-financial answers and unresolved issues have received their own review.
Discuss your US reporting records
Causeway supports configurable finance, reporting, approval and recordkeeping controls within a global NGO operating platform. Evaluate those controls against your reviewed requirements for US nonprofit return preparation and financial, programme and governance workpapers. Use a return-preparation workpaper to trace one financial total and one programme statement. Agree who reviews adjustments and how the approved submission and supporting records remain connected.
Frequently asked questions
Does every nonprofit file Form 990?
No. Filing requirements and exceptions depend on the organisation's status and circumstances, and other returns or notices may apply. Consult the relevant IRS instructions and qualified tax advice. Do not choose a form solely because the organisation describes itself as a nonprofit.
Can ERP submit a return automatically?
Only a specifically supported and appropriate filing workflow could do so; a financial export does not establish that capability. Confirm the exact service, current form support, authorisation and review responsibilities. Keep preparation and submission requirements separate in the scope.
Which records need review beyond ledger totals?
Depending on the applicable filing, programme descriptions, governance information and other supporting details may require separate owners and evidence. Map each required item to its source. A reconciled ledger remains essential but does not validate every non-financial statement.