French association reporting should be designed from the association's circumstances, not from a universal NGO checklist. Legal status, activities, funding arrangements and other conditions can affect the records and reports required. A software configuration is useful only after those requirements have been identified.
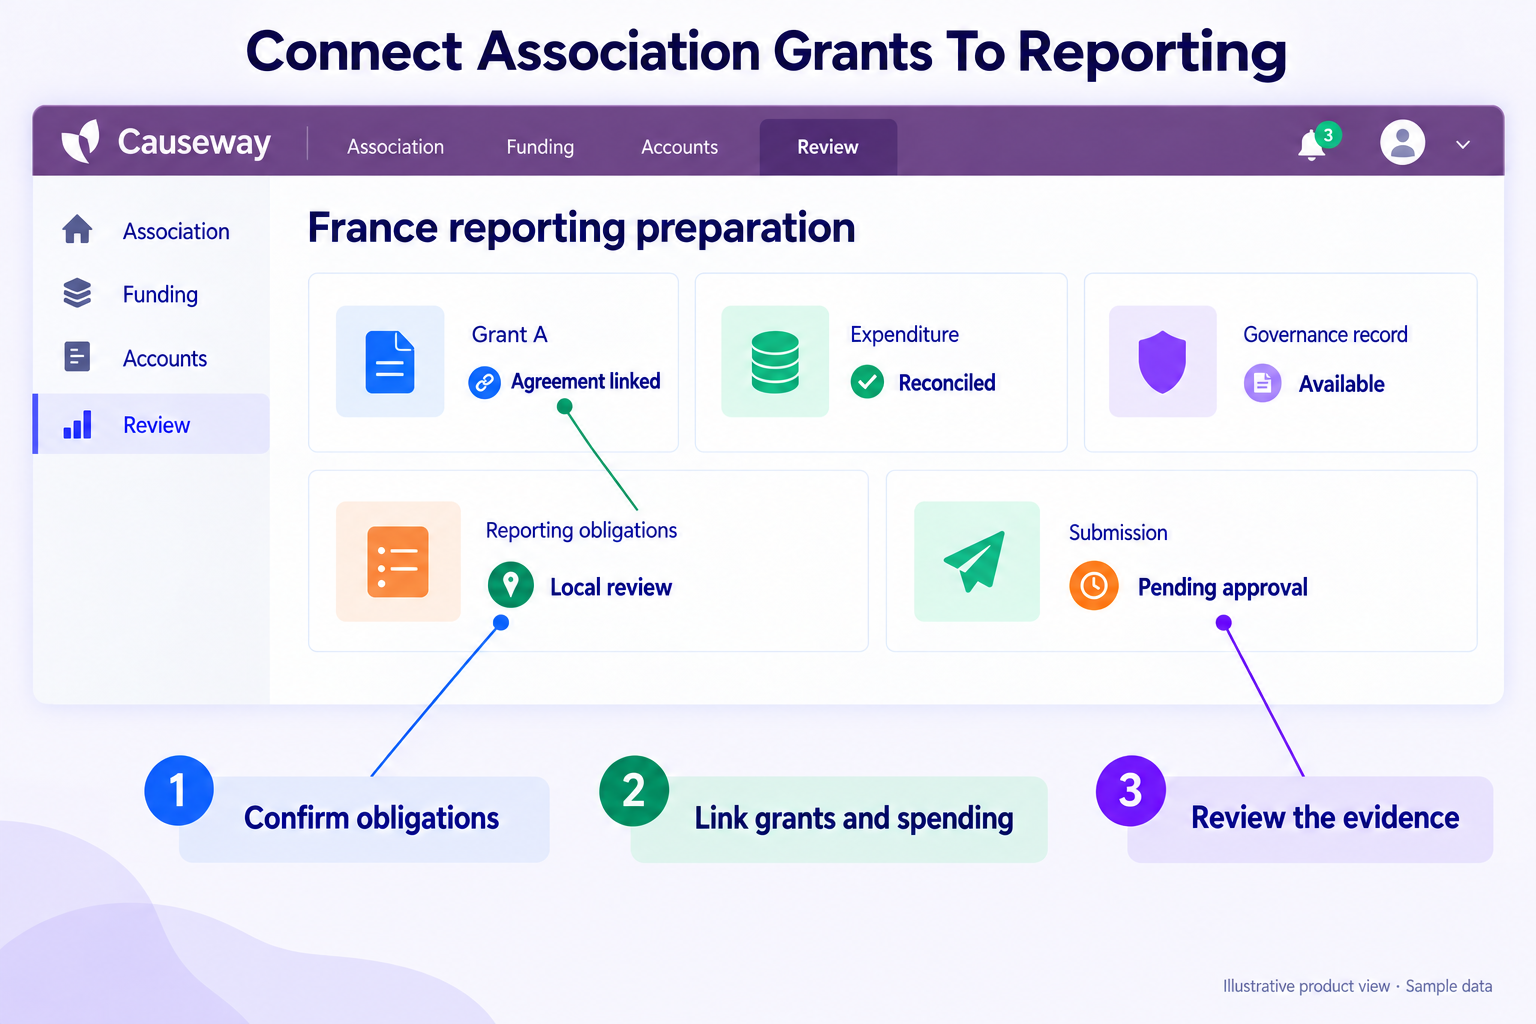
Build an evidence workflow connecting accounts, grants and programme records to the relevant reviews and submissions. Keep local reporting responsibilities distinct from a global management dashboard. They can share source data while using different classifications, periods or approval processes.
The association and its funding define applicability
Record the association's legal identity, governing arrangements, activities and funding sources. Identify employment, commercial activity, public funding or other circumstances that require specialist review. Do not assume that two associations have identical obligations because they deliver similar programmes.
The official association accounting guidance explains that accounting requirements vary with circumstances including size, funding and activities. Use current authoritative guidance and a qualified local adviser to determine the applicable accounting and reporting approach.
The compliance register should preserve the source, applicability decision, owner and review date. Include grant-agreement obligations separately from statutory or governance requirements so a change in one does not silently alter the others.
Accounting and grant reports share controlled source records
Create a mapping between source transactions, local account classifications, programme dimensions and grant reporting lines. Assign ownership and retain effective versions. A global account label may need additional local classification before it supports an association's reporting needs.
The grant lifecycle should preserve agreements, eligible periods, budgets and amendments. Record who reviewed each operational condition and how unresolved questions are handled before spending. Do not infer eligibility solely from a project code.
| Evidence Group | Question To Resolve |
|---|---|
| Association records | Which entity and governing decisions does the report concern? |
| Accounts | Which reviewed records and classifications support the totals? |
| Grant conditions | What expenditure and reporting terms apply? |
| Activities | What evidence supports the delivery statement? |
| Approvals | Who reviewed and authorised the final output? |
Test the mapping with a small period containing a correction and a shared cost. A clean dataset with only direct expenses can hide allocation and versioning problems.
A shared cost needs an approved allocation
The donor reporting workflow aligns expenditure with the relevant period, budget line and programme evidence. Apply the same discipline to grant-related reporting for the association. A payment date alone may not establish the period or treatment required by the applicable instructions.
Suppose that in one project, one event serves two funded activities. Document the allocation basis for venue and staff costs, preserve the source evidence and have the responsible reviewer approve the treatment. Linking the event to two grants should not duplicate the expense in the combined report.
Keep programme measures separately defined. Attendance records can support an activity statement, but they do not establish every outcome claim. Use appropriate aggregate reporting and access controls for participant information, especially when sharing reports outside the association.
Review and publication duties depend on circumstances
The official accounting and publication guidance describes obligations for associations receiving annual subsidies above the specified legal threshold, including accounts, auditor involvement and publication requirements. Confirm whether that provision and any other relevant rules apply to the association before configuring deadlines or approvals.
Avoid hard-coding a single threshold or submission workflow across every association in a global system. Preserve the applicability decision and source so changes can be reviewed. An obligation arising from a funding arrangement may also require a separate deadline or evidence pack.
Create a calendar identifying preparation, approval, publication or submission, and retained evidence. Keep the exact authorised documents and confirmation of the relevant action. Retention decisions should be reviewed by record category and applicable requirement rather than set to a single global default.
Validate local requirements and dates
The local configuration approach should distinguish shared controls from French reporting mappings and other justified variations. Have the appropriate local specialist review the design before it becomes an acceptance criterion.
Test a complete reporting sequence: select the period, produce the mapped figures, resolve an exception, review the narrative, approve the output and retrieve the supporting records. Confirm that a later mapping change does not make the earlier submission impossible to reproduce.
Keep the configuration and requirement register under review when activities, funding or organisational circumstances change. A setting that was appropriate for one period may need reassessment after a material change. Assign an owner to that review rather than relying on the implementation supplier to infer it.
Keep grant reporting distinct from annual accounts
An association can need an annual accounting output and a separate report on a funded activity. Preserve the agreement, approved budget and allocation method behind the activity report. Reconcile its expenditure to the accounts while explaining differences in period or scope.
Assign responsibility for the applicability decision and the final submission. A provider's general French localisation claim should be checked against the association's actual status, activities and funding conditions before configuring the reporting process.
One funded activity, two reporting views
For a worked €1,000 venue invoice, an approved usage basis allocates €600 to Activity A and €400 to Activity B. The accounts retain the full invoice with its local classification; the grant schedules use the relevant allocations and agreement periods. Linking the invoice to both activities must not create €2,000 of reported cost.
Keep a review record with entity, period, funding arrangement, source URL, source version, applicability decision, reviewer and next review date. The review date is an actual assigned date, not an automatic assumption that last year's mapping remains valid. A change in funding terms triggers reassessment of the affected grant schedule even if the annual accounts mapping remains unchanged.
Map each obligation to its control, evidence and reviewer in the Global Compliance Controls Matrix. Keep association accounts and donor-funded activity reports aligned without treating their reporting periods as interchangeable.
Conclusion
Keep the association's annual accounts and each grant report connected to controlled source records, while preserving their different periods and definitions. Reconcile shared-cost allocations and retain the basis for each adjustment. The applicable review and publication duties follow the association's circumstances, so confirm them before configuring the output. At close, the team should be able to explain why the same funded activity appears differently in two reports without changing the underlying facts.
Discuss your association reporting workflow
Causeway supports configurable finance, reporting, approval and recordkeeping controls within a global NGO operating platform. Evaluate those controls against your reviewed requirements for French association accounts, funded activities and grant reporting. Bring one funded activity with a shared cost and different grant and annual-account periods. Follow its approved allocation into both reports, keeping each calculation, reviewer and supporting record visible.
Frequently asked questions
Do all associations have the same accounting duties?
No. Relevant circumstances can include legal arrangements, activities, funding and other conditions. Use current official guidance and qualified local review to determine the appropriate approach. Do not copy another association's configuration without checking applicability.
Can grant conditions add reporting requirements?
Yes, an agreement can impose reporting and evidence obligations in addition to other applicable duties. Record the terms, deadlines and approval responsibilities separately. Check amendments and preserve the basis used for each submission.
Which records should support a grant report?
Use the agreement, approved budget, relevant transactions, allocation evidence and programme records needed for the report's statements. Reconcile the figures and retain review approvals. The exact pack depends on the funding conditions and applicable requirements.